For finance directors, HR managers, and registrars at universities and TVET colleges, payroll is never simply a monthly transaction. It is one of the most regulated, most scrutinised, and most consequential processes an institution runs. Getting it wrong carries financial penalties, reputational damage, and in some cases, legal liability. Yet a surprisingly common challenge across African higher education institutions is that payroll still operates as a silo, disconnected from the student, finance, and HR data that should inform it. The argument for payroll integration in higher education is not theoretical. It is rooted in the very real risks that siloed payroll creates every single day.
The Hidden Cost of Siloed Payroll in Higher Education

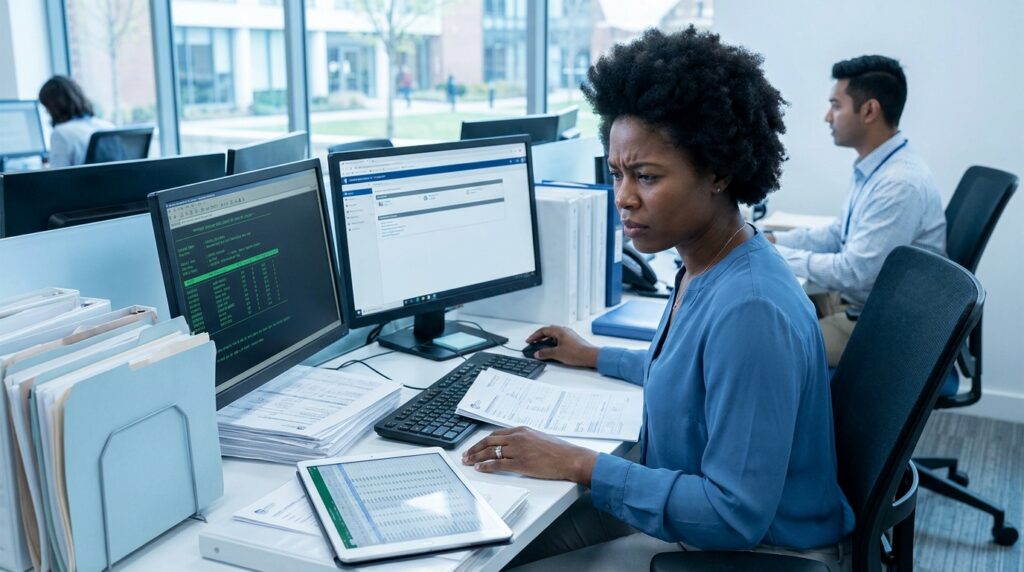
When payroll systems are not integrated with the broader institutional ERP, data has to travel between systems manually. Staff capture employee records in one system, update leave in another, manage tax directives in a spreadsheet, and then reconcile everything before a pay run. Each handoff is an opportunity for error. Each manual step is a potential compliance gap.
The consequences of this fragmentation are felt across the institution:
- Duplicate or outdated employee records lead to incorrect salary calculations, ghost employee payments, or missed terminations on the payroll.
- Leave balances that do not sync in real time result in incorrect leave pay-outs, particularly on termination, which creates both financial exposure and potential CCMA liability.
- Manual statutory submissions increase the risk of late or inaccurate PAYE, UIF, and SDL filings with SARS, triggering penalties and interest.
- Audit trails are incomplete because changes made in one system are not automatically reflected and time-stamped in another.
- Reporting is slow and unreliable, because finance and HR teams spend days consolidating data that an integrated system would surface instantly.
For institutions already operating under financial pressure and increasing scrutiny from funding bodies and government oversight structures, these are not minor inconveniences. They are genuine governance risks.
Payroll Integration in Higher Education: What It Actually Means

True payroll integration is not simply about connecting two software products via an export file or a nightly batch process. It means that HR, payroll, finance, and leave management share a single source of truth within one unified ERP environment. When an employee’s contract is updated in HR, that change flows through to payroll automatically. When a staff member submits a leave request, the approved leave immediately adjusts their payable hours for the month. When a new appointment is made, the position is linked to the correct cost centre in the general ledger from day one.
This level of integration is what differentiates a purpose-built higher education ERP from a generic payroll tool bolted onto a student system. It is also what makes integrated HR ERP in education a strategic investment rather than a technology expense.
Why Higher Education Payroll Is More Complex Than Other Sectors
Universities and TVET colleges face payroll complexity that most private sector organisations do not encounter. Consider the range of employment types typically managed within a single institution:
- Permanent academic and administrative staff on different salary scales and grading structures
- Contract and fixed-term employees, often tied to research funding cycles
- Part-time and sessional lecturers paid on a claims basis
- Postgraduate students on stipends or bursaries that may have tax implications
- Staff seconded from or to other public institutions
Each of these categories has different statutory treatment, different leave entitlements, and different reporting requirements. Managing this complexity without an integrated system means that the margin for error is wide, and the audit exposure is significant.
South African Statutory Compliance: Where the Risk Is Highest
South African higher education institutions operate within a demanding statutory environment. Higher education payroll compliance requires accurate and timely adherence to obligations administered by multiple regulatory bodies.
SARS Obligations
PAYE, UIF, and SDL contributions must be calculated correctly for every employee category, submitted via the SARS eFiling platform, and reconciled through the bi-annual EMP501 process. The introduction of the SARS filing season has made accurate, real-time employee tax data non-negotiable. Errors in IRP5 data, late EMP201 submissions, or incorrect tax directive applications all carry financial penalties. For institutions with hundreds or thousands of staff, the volume of transactions makes manual processing both impractical and high-risk.
UIF and the Department of Employment and Labour
Every employer is required to register employees for UIF and submit accurate declarations. When payroll is siloed and employee status changes (such as contract renewals, terminations, or maternity leave) are not captured in real time, UIF declarations become unreliable. This creates risk both for the institution and for the employees who depend on those contributions when they claim.
National Student Financial Aid Scheme (NSFAS) and Third-Party Deductions
Many higher education institutions manage complex third-party deduction environments, including pension and provident fund contributions, medical aid schemes, garnishee orders, and institutional loan repayments. Ensuring these deductions are calculated correctly, paid over to the correct beneficiaries, and reconciled every month requires the kind of systematic control that only an integrated system can provide.
Public Sector Reporting Requirements
For public universities and TVET colleges, the reporting obligations extend beyond SARS. Institutions must comply with the requirements of the Department of Higher Education and Training, submit accurate headcount and expenditure data for subsidy purposes, and in many cases align their payroll classifications to the public sector pay framework. When payroll data is not integrated with HR and finance, producing accurate management accounts and statutory reports becomes a significant manual exercise that delays decision-making and increases the likelihood of misstatement.
The Pan-African Picture: Compliance Beyond South Africa
For institutions operating across multiple African countries, or for those looking at regional campuses and collaborative programmes, the compliance picture becomes even more complex. Tax legislation, provident fund requirements, and labour law vary significantly across the continent. HR payroll software for universities operating in this environment needs to be flexible enough to accommodate country-specific statutory requirements without requiring a separate system for each jurisdiction.
This is a reality that Adapt IT Education understands as a proudly African business, one that has been supporting institutions across the continent for decades. The ability to configure payroll rules, statutory rates, and reporting formats for different regulatory environments within a single platform is not a luxury for pan-African institutions. It is a fundamental requirement.
How ITS Integrator Addresses Payroll Risk Natively
ITS Integrator is Adapt IT Education’s purpose-built ERP for higher education, and its HR and payroll modules are designed specifically for the complexity that universities and TVET colleges face. Rather than integrating with a third-party payroll engine, the HR and payroll functionality is native to the platform, sharing the same database and business logic as the finance, student, and academic modules.
A Single Employee Record Across HR, Payroll, and Finance
Every employee in ITS Integrator exists as a single record. Changes to personal information, employment status, grading, or cost centre allocation are made once and flow through to all relevant modules automatically. This eliminates the duplicate-entry risk that causes so many payroll errors in siloed environments.
Automated Statutory Calculations and Submissions
ITS Integrator maintains up-to-date tax tables and statutory rates, ensuring that PAYE, UIF, and SDL calculations are accurate without requiring manual updates when legislation changes. The system supports the generation of IRP5 certificates, EMP201 and EMP501 submissions, and reconciliation reports in the formats required by SARS.
Leave Integration with Real-Time Payroll Impact
Leave taken, approved, and processed in the HR module is immediately reflected in the payroll calculation for the relevant period. This means leave pay-outs on termination are accurate, unpaid leave deductions are applied correctly, and there is no end-of-month reconciliation exercise to align leave records with payroll.
Audit Trail and Role-Based Access Control
Every change made within the HR and payroll modules is logged with a timestamp, a user identifier, and a before-and-after record of the data that changed. This built-in audit trail means that institutions can respond to internal audit queries, external audit requirements, and SARS verifications with confidence and speed. Role-based access control ensures that sensitive payroll data is only accessible to authorised staff, reducing the risk of unauthorised changes.
Cost Centre Reporting Aligned to Finance
Because ITS Integrator’s payroll module is natively integrated with the general ledger, payroll costs are posted directly to the correct cost centres, projects, and funding sources at the point of processing. Finance managers receive accurate, real-time visibility into staff expenditure without waiting for manual journal entries from HR.
Practical Steps for Institutions Considering Integration
If your institution is currently running payroll on a standalone system or a generic tool that does not connect to your student and finance ERP, there are some immediate questions worth asking:
- How long does it take to produce a reconciled payroll report? If the answer is measured in days rather than hours, the manual overhead is a risk indicator.
- How confident are you in the accuracy of your IRP5 data before each filing season? Uncertainty here points to data integrity gaps between systems.
- When an employee’s contract changes, how many systems need to be updated? Every system that requires a separate update is a potential point of failure.
- Can you produce a complete payroll audit trail for any pay period in under an hour? If not, your audit readiness is lower than it should be.
These are not trick questions. They are the diagnostic questions that experienced higher education finance and HR professionals ask when evaluating whether their current environment is managing risk effectively.
Integration Is Not Just Efficiency. It Is Risk Management.
The case for payroll integration in higher education is ultimately a governance case. It is about giving institutional leadership confidence that the largest single line item in most university budgets is being managed with accuracy, transparency, and full statutory compliance. It is about protecting the institution from penalties, audit findings, and reputational risk. And it is about giving HR and finance teams the tools to focus on strategic work rather than manual reconciliation.
Adapt IT Education has been partnering with universities and TVET colleges across Africa for over three decades. We understand the statutory environment, the institutional complexity, and the specific pressures that higher education leaders face. ITS Integrator’s integrated HR and payroll modules are built on that understanding, not adapted from a generic commercial product.
If your institution is ready to move beyond siloed payroll and build a genuinely integrated HR and finance environment, we would welcome the conversation.
Contact the Adapt IT Education team today to find out how ITS Integrator can reduce your institution’s payroll risk and strengthen your compliance posture across every statutory obligation.